Manufactured and Mobile Homes in Washington: Titling and Sale
Navigating a washington manufactured home sale real estate transaction requires a specialized understanding of state laws, licensing regulations, and property classifications. Unlike traditional site-built residential properties, manufactured and mobile homes occupy a unique legal space where personal property law intersects with real property law. For real estate brokers in Washington, mastering these distinctions is not just a matter of professional competence; it is essential for protecting clients from costly legal and financial pitfalls.
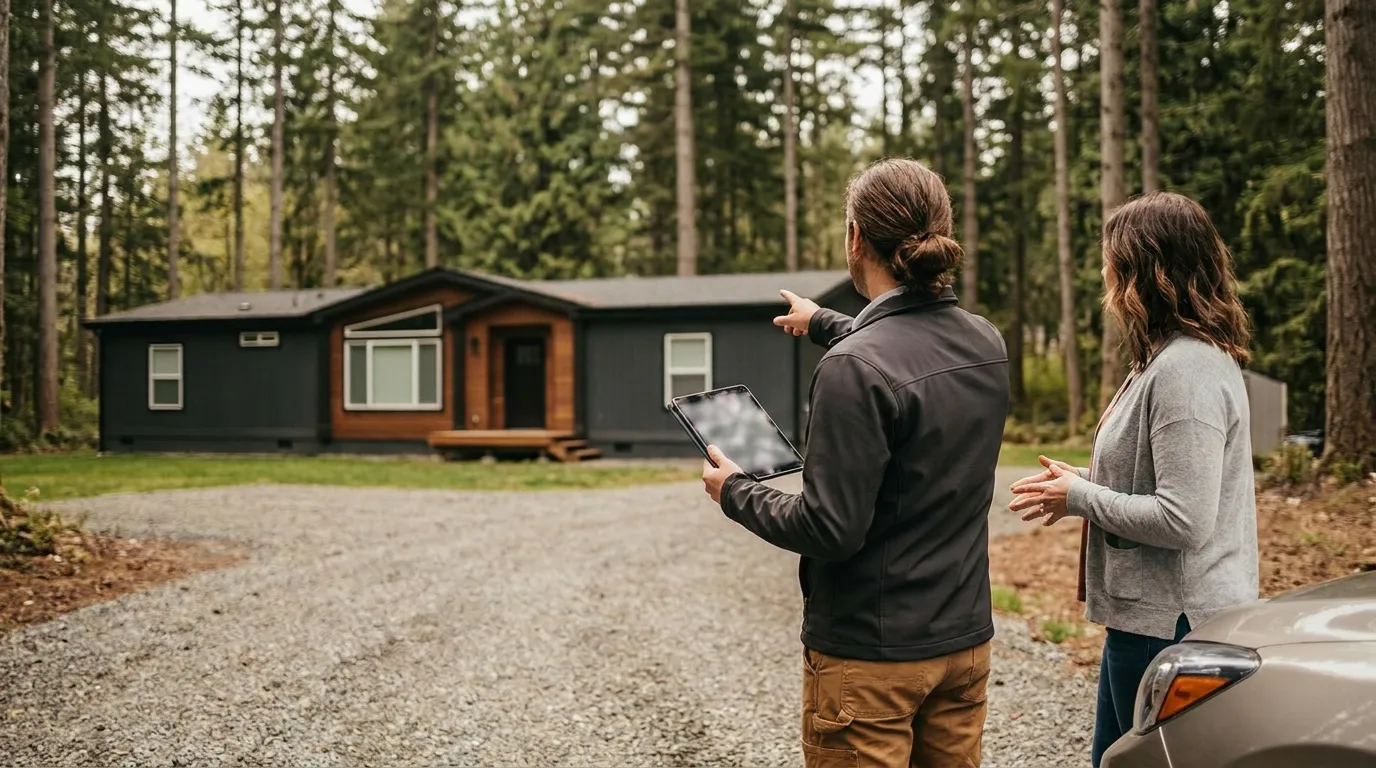
Whether you are representing a buyer looking at a home in a manufactured housing community or a seller listing a manufactured home on acreage, you must understand how Washington treats these structures. This guide covers the critical aspects of titling, title elimination, park leases, financing hurdles, and mandatory disclosures. If you are completing your first active renewal cycle, mastering these concepts is a vital step. You can fulfill your state-mandated education requirements by enrolling in our comprehensive Washington 90-Hour First Renewal Package.
Real Property vs. Personal Property Titling
In Washington, a manufactured home is initially classified as personal property (chattel), much like a vehicle. When manufactured, it is issued a vehicle title by the Washington State Department of Licensing (DOL). As long as the home retains this title, it is legally distinct from the land on which it sits, even if it is physically placed on a concrete foundation. This classification has significant implications for taxation, transfer of ownership, and financing.
To verify current titling status, fees, and specific administrative rules, real estate professionals should consult the official Washington State Department of Licensing website. When a manufactured home is sold as personal property, the transaction is typically processed through the DOL or an authorized vehicle licensing agent, rather than through a standard real estate deed transfer. Conversely, when a manufactured home is legally classified as real property, it is treated as an improvement to the land, and ownership transfers via a traditional statutory warranty deed or bargain and sale deed.
Elimination of Title and the Forms Involved
To convert a manufactured home from personal property to real property, the owner must go through a formal legal process known as "title elimination." This process permanently bonds the manufactured home to the land, removing its vehicle status. Title elimination is highly desirable because it simplifies future real estate transactions and opens up more favorable financing options for buyers.
The title elimination process in Washington involves several key steps and specific documentation:
- Manufactured Home Application: The property owner must complete a Manufactured Home Application form, which is submitted to the local county auditor's office.
- Land Ownership: The owner of the manufactured home must also own the land on which the home is placed, or have a qualifying long-term lease.
- Permits and Inspections: The home must be installed on a permanent foundation system in accordance with local building codes and Washington State Department of Labor & Industries (L&I) standards.
- Recording: Once approved by the county and the DOL, the application is recorded in the county real property records, effectively eliminating the vehicle title.
Brokers must verify whether title elimination has actually occurred before listing a property. Do not rely solely on MLS remarks; always check the county tax assessor's records and look for a recorded Manufactured Home Application.
Park-Owned Land and Lease Considerations
Not all manufactured homes sit on land owned by the homeowner. Many are located in manufactured housing communities, commonly referred to as mobile home parks. In these scenarios, the buyer purchases the manufactured home (personal property) and leases the land (the lot) from the park owner. This arrangement introduces unique legal dynamics governed by the Washington Manufactured/Mobile Home Landlord-Tenant Act (RCW 59.20).
When representing a buyer in a park-owned land transaction, brokers must ensure their clients understand the following:
- Park Approval: The purchase contract must be contingent upon the buyer receiving formal approval from the park management to lease the lot.
- Lease Terms: Buyers must carefully review the park rules, rental rates, utility fees, and lease duration. Park owners are generally required to offer a written one-year lease.
- Right of First Refusal: In Washington, manufactured home park tenants have specific rights if the park owner decides to sell the community, which can impact long-term stability.
Financing Limitations for Manufactured Homes
Securing financing for a manufactured home can be significantly more challenging than securing a conventional mortgage for a site-built home. Lenders view manufactured homes as higher risk, and their guidelines are strict. Understanding these limitations helps brokers set realistic expectations for their buyers.
Key financing hurdles include:- Foundation Requirements: Most conventional, FHA, and VA lenders require the home to be on a permanent foundation that meets HUD guidelines, certified by a licensed structural engineer.
- Age of the Home: Many lenders will not finance manufactured homes built before June 15, 1976, which is when the federal HUD safety standards went into effect.
- Title Elimination: To qualify for standard residential mortgages (such as FHA, VA, or conventional conforming loans), lenders almost always require that the title be eliminated prior to or at the time of closing.
- Chattel Loans: If the home is in a park and the land is leased, buyers must secure a "chattel loan" rather than a traditional mortgage. Chattel loans typically carry higher interest rates and shorter repayment terms.
Disclosure Specifics for Manufactured Home Sales
Washington law requires sellers of residential real property to provide buyers with a completed Seller Disclosure Statement (Form 17). However, when a manufactured home is sold as personal property (e.g., in a park), the disclosure requirements can vary. Regardless of the legal classification, full transparency is critical to avoid post-closing litigation.
Sellers must disclose any known material defects specific to manufactured homes, including:
- Structural Integrity: Any modifications made to the home, such as additions or roof alterations, which require permits and L&I insignia tags.
- Water Intrusion: Manufactured homes are particularly susceptible to water damage around window seals, roof seams, and underbelly insulation.
- Utility Connections: The condition and legality of hookups for water, sewer, septic, and electrical systems.
As you guide clients through these complex transactions, staying compliant with state laws is paramount. If you are preparing for your upcoming license renewal, ensure you have the latest legal updates by registering for our comprehensive Washington 90-Hour First Renewal Package to satisfy your Washington First Renewal requirements seamlessly.
Frequently Asked Questions
Can I sell a manufactured home in Washington if the title is lost?
Yes, but the seller must first obtain a duplicate title or file an Affidavit of Loss/Release of Interest with the Washington Department of Licensing before the transfer of ownership can be legally completed.
What is an L&I red tag on a Washington manufactured home?
An L&I red tag indicates that unpermitted alterations were made to the manufactured home. To resolve this, an inspector from the Washington Department of Labor & Industries must inspect the modifications, approve them, and issue an insignia of approval before the home can be sold or financed.
Does a manufactured home sale require an escrow agent?
While not legally required for simple personal property transfers, using a licensed escrow agent is highly recommended for all manufactured home sales to ensure that taxes are cleared, liens are satisfied, and title transfer documents are correctly filed with the state.