Contingencies in Washington Contracts: Inspection, Financing, Title, and Sale
In Washington State, purchase and sale agreements are built on a foundation of contingencies. These contractual clauses act as safety valves, allowing buyers to walk away from a transaction with their earnest money intact if specific conditions are not met. For real estate brokers, mastering the nuances of these contingencies is not just a matter of closing deals—it is a fundamental duty to protect your clients from severe financial and legal liability. Whether you are navigating a hot seller's market in Seattle or a balanced market in Spokane, understanding how to draft, execute, and waive these contingencies is critical.
As a newly licensed broker preparing for your first renewal, the Washington Department of Licensing (DOL) requires specific continuing education to ensure you maintain high standards of practice. Navigating complex contract forms, such as those provided by the Northwest Multiple Listing Service (NWMLS), requires deep technical knowledge. To fulfill your mandatory education hours and gain confidence in contract management, you can enroll in our comprehensive Washington 90-Hour First Renewal Package, designed specifically to satisfy state requirements while elevating your transaction skills.
Each Contingency and What It Actually Protects
Every contingency in a Washington real estate contract serves a distinct protective purpose, shifting the balance of risk between the buyer and the seller. The four most common contingencies are inspection, financing, title, and house sale.
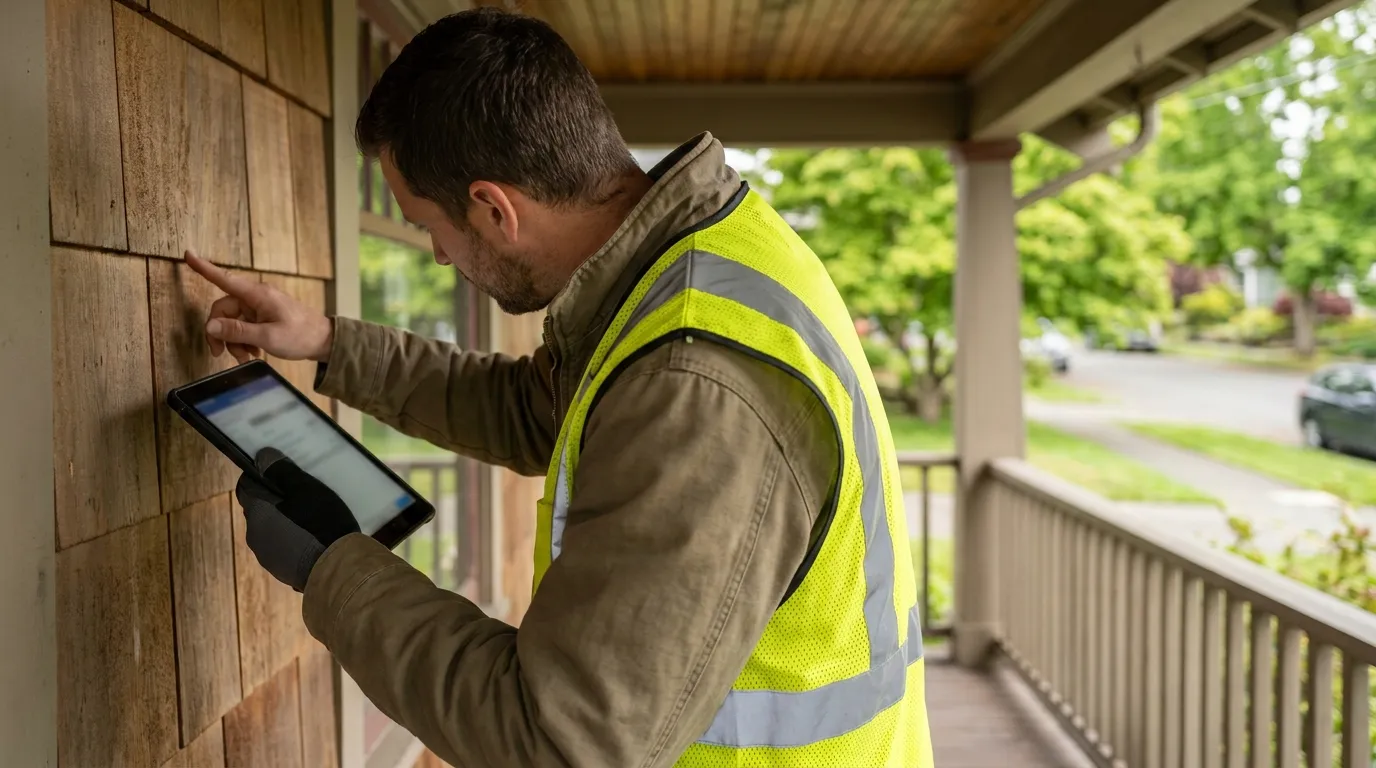
The Inspection Contingency (Form 35) protects the buyer's right to assess the physical condition of the property. It allows the buyer to hire licensed inspectors to evaluate the structure, roof, pest activity, sewer line, and other systems. If defects are found, the buyer can negotiate repairs, request a price reduction, or terminate the contract and receive a full refund of their earnest money deposit.
The Financing Contingency (Form 22A) protects the buyer in the event that their mortgage lender fails to approve the loan. This contingency outlines the terms of the loan the buyer is seeking and provides a structured process for the seller to request updates. If the buyer, despite making a good faith effort, cannot secure financing, this clause prevents them from being sued for breach of contract and ensures the return of their earnest money.
The Title Contingency (Form 22T or standard contract terms) ensures the buyer receives "marketable title" free of unexpected liens, easements, or encumbrances. It gives the buyer a set window of time to review the preliminary title report. If restrictive covenants or unresolved liens are discovered that the seller cannot or will not clear, the buyer can terminate the transaction.
The Sale of Property Contingency (Form 22B) protects buyers who must sell their current home before they can afford to purchase a new one. This contingency prevents the buyer from being obligated to purchase two homes simultaneously, making the transaction contingent on the successful closing of their existing property within a specified timeframe.
Waiver Strategies in Competitive Markets and Their Risks
In highly competitive Washington markets, buyers often face multiple-offer scenarios. To make their offers more appealing to sellers, some buyers choose to waive contingencies. While this strategy can make an offer stand out, it introduces immense financial and legal risks that brokers must clearly explain to their clients.
Waiving the inspection contingency means the buyer accepts the property entirely "as-is." If major structural failures, mold, or sewer collapses are discovered after closing, the buyer has no recourse against the seller and must cover the repair costs out of pocket. To mitigate this, brokers often recommend a "pre-inspection," where the buyer conducts an inspection before submitting an offer, though this requires upfront financial investment with no guarantee of contract acceptance.
Waiving the financing contingency is even riskier. If a buyer waives this contingency and their loan is subsequently denied—due to a sudden job loss, an interest rate spike, or a low appraisal—they will forfeit their earnest money deposit, which often represents 1% to 5% of the purchase price. Furthermore, they could face additional legal action from the seller for damages. Brokers must document that they advised clients of these risks in writing to protect themselves from future liability claims.
Timelines and Notice Requirements under NWMLS Rules
In Washington real estate transactions, time is of the essence. Every contingency is governed by strict timelines, typically measured in calendar days. Under NWMLS rules, unless otherwise specified, days are calculated starting the day after mutual acceptance. If a deadline falls on a weekend or a legal holiday, it is automatically extended to the next business day, except for possession dates.
For example, the standard timeline for an inspection contingency is 10 days, though this is frequently negotiated to a shorter window. Within this period, the buyer must complete all inspections and deliver a formal notice (Form 35R) to the seller. The notice must state whether the buyer is approving the inspection, terminating the agreement, or requesting specific repairs or additional time for further inspections.
The financing contingency also features a multi-step timeline. Typically, the buyer has a set number of days (often 21 to 30) to secure a loan commitment. Additionally, the seller has the right to request that the buyer waive the financing contingency after a certain number of days (using Form 22AR). If the buyer fails to respond or waive the contingency within the required timeframe after receiving this notice, the seller may have the right to terminate the contract.
What Happens When a Deadline Passes Silently
One of the most critical lessons for a new broker is understanding the consequences of silence. In Washington real estate contracts, failing to take action before a contingency deadline passes is legally binding and almost always favors the other party.
If the inspection contingency deadline passes and the buyer has not submitted Form 35R, the contingency is deemed waived. The buyer is now legally obligated to proceed with the purchase without any repairs or price concessions, and they can no longer use physical defects as a reason to terminate the contract and recover their earnest money.
Similarly, if a buyer fails to object to the preliminary title report within the specified timeframe, they are deemed to have accepted the title condition, including any restrictive covenants or easements. Brokers must maintain a rigorous tracking system for all contract deadlines. Missing a deadline due to administrative oversight is a primary cause of licensing complaints and professional liability lawsuits in Washington.
For official guidelines on licensing laws and professional conduct, you can visit the Washington Department of Licensing website.
Client Conversation Scripts for Washington Brokers
Explaining complex legal contingencies to emotional buyers and sellers requires clear, calm, and professional communication. Here are two scripts you can use to guide your clients through these critical decisions.
Script 1: Advising a Buyer Against Waiving a Financing Contingency
"I understand that we are in a competitive multiple-offer situation and you want your offer to look as strong as possible. However, waiving the financing contingency carries significant risk. If we waive this clause and your loan is denied for any reason—such as an unexpected change in interest rates or an appraisal shortfall—you will lose your entire earnest money deposit of $20,000, and the seller could potentially sue you for further damages. My recommendation is to keep the financing contingency in place, but we can make your offer competitive in other ways, such as shortening the timeline or increasing your earnest money deposit."
Script 2: Explaining the Inspection Response to a Seller
"The buyers have completed their home inspection and have requested three repairs on Form 35R: repairing the water heater, replacing a broken window, and servicing the furnace. We have three business days to respond. We have three options: we can agree to all requests, negotiate a credit instead of doing the repairs ourselves, or reject the requests. Keep in mind that if we reject their requests entirely, the buyers have the right to terminate the contract and walk away with their earnest money. Let's look at the cost of these repairs and decide on a strategy that keeps the transaction moving forward smoothly."
Mastering these conversations and contract mechanics is essential for building a successful, referral-based real estate practice. To ensure you are fully prepared to handle these complex scenarios while meeting your state-mandated education requirements, consider enrolling in our comprehensive Washington 90-Hour First Renewal Package today. Our expert-designed curriculum provides the practical knowledge and legal confidence you need to protect your clients and thrive in the Washington real estate market.
Frequently Asked Questions
Can a buyer perform a sewer scope under a standard Form 35 inspection contingency?
Yes, but it is highly recommended to explicitly include the sewer scope in the inspection terms or use the specific Sewer Inspection Addendum (Form 35N) to avoid any disputes with the seller regarding invasive testing or access to the property's waste lines.
What is the difference between a feasibility contingency and an inspection contingency?
An inspection contingency (Form 35) focuses on the physical condition of existing structures. A feasibility contingency (Form 35F) is typically used for vacant land or commercial properties, allowing the buyer to investigate zoning laws, utility availability, environmental factors, and overall suitability for development.
Can a seller back out of a contract if the buyer requests repairs?
No. If the buyer requests repairs using Form 35R, the seller has the right to agree, negotiate, or refuse. However, the seller cannot unilaterally terminate the contract simply because the buyer asked for repairs; the power to terminate remains with the buyer if the parties cannot reach an agreement on the repairs.